Pick an effective date and define what is changing
A conversion from 1099 treatment to W-2 employment should be more than changing a dropdown in payroll software. Write down the effective date, the role, manager, compensation structure, work location, and reason for the change. From that date forward, the company should operate the relationship as employment and meet the federal and state obligations that follow.
Do not backdate an employee start date merely to make the records look cleaner. If prior contractor treatment may have been wrong, review the earlier period separately.
- Before effective dateTie contractor payments to genuine prior services.
- Effective dateDocument role, manager, pay, and location.
- After conversionUse employee onboarding and payroll systems.
- Year endReconcile payroll, vendor ledger, and forms.
- Historical reviewAssess earlier periods separately.
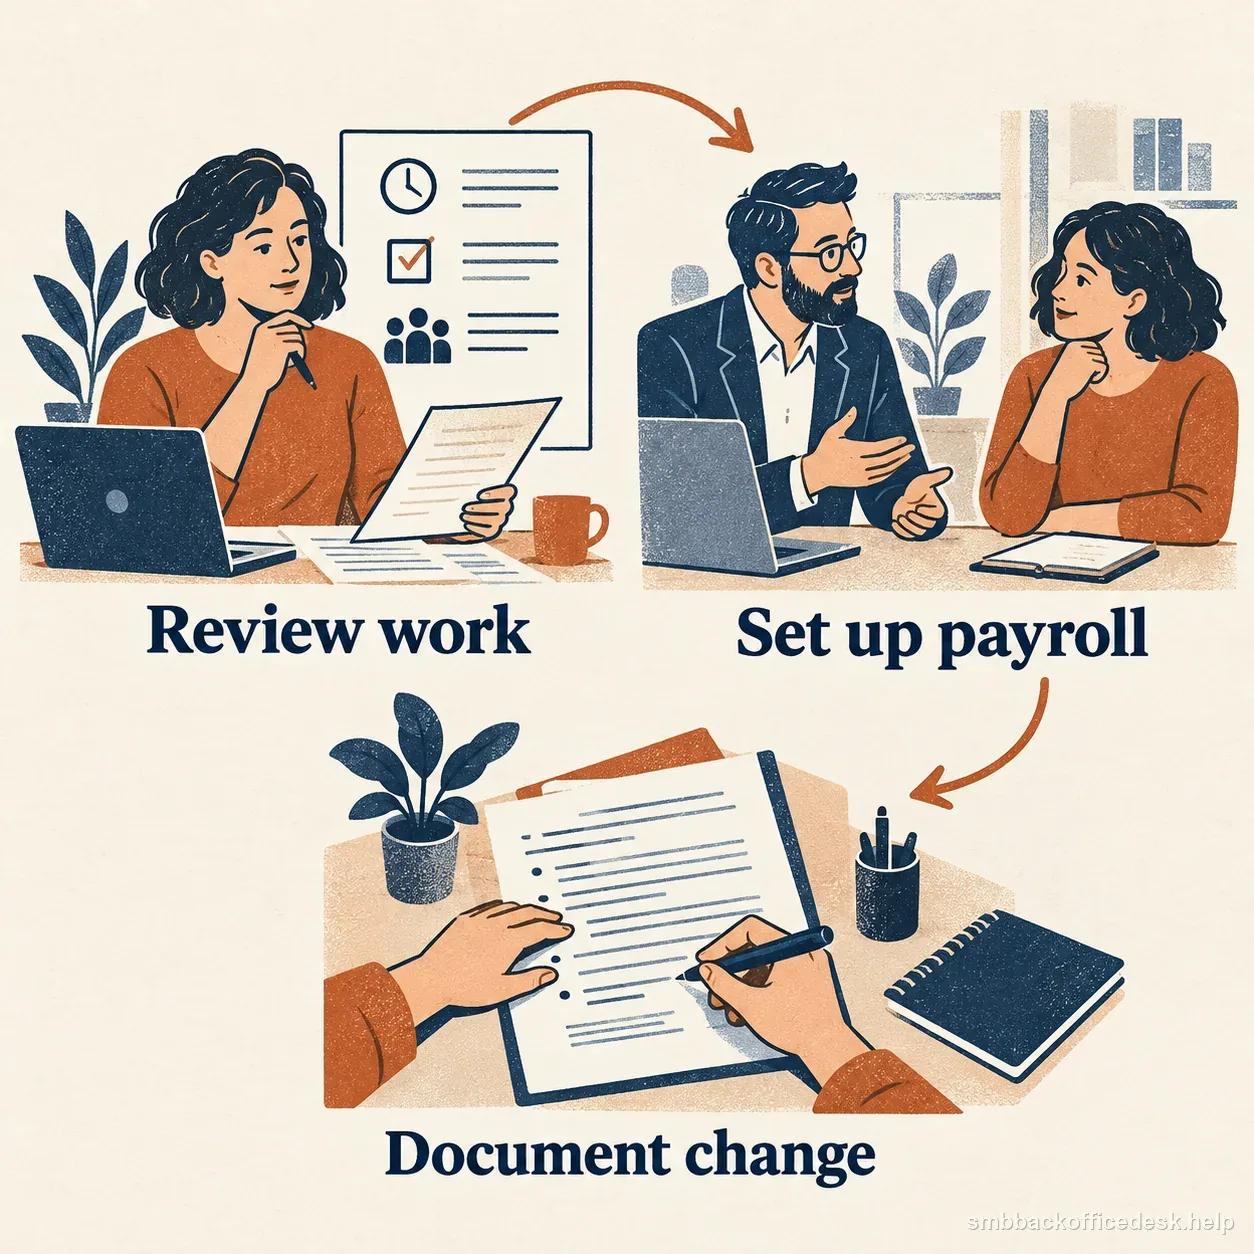
A defined cutover links the prior vendor file, employee start steps, and a first-payroll check.
Complete employee onboarding
Before the employee starts under the new status, collect the current Form W-4 for federal income-tax withholding and complete Form I-9 employment-eligibility verification on time. The employee completes Section 1 after accepting the job offer and no later than the first day of employment. The employer generally completes Section 2 within three business days after the first day of work for pay; if the job lasts fewer than three business days, Section 2 is due no later than the first day. Follow current USCIS instructions for authorized examination methods and reverification, and current IRS instructions for the W-4. For Form I-9, let the employee choose acceptable documents from the current lists; do not demand a particular document or proof of citizenship based on perceived status.
Set up the person in payroll with the correct legal name, Social Security number, work location, pay frequency, compensation, and withholding elections. Determine state and local withholding and new-hire reporting requirements for the employee’s actual work state.
Enroll the worker in timekeeping if the role is nonexempt. Configure overtime, meal/rest rules where applicable, paid leave, and wage-statement requirements under the governing jurisdiction. Classification as an employee can change much more than the year-end tax form.
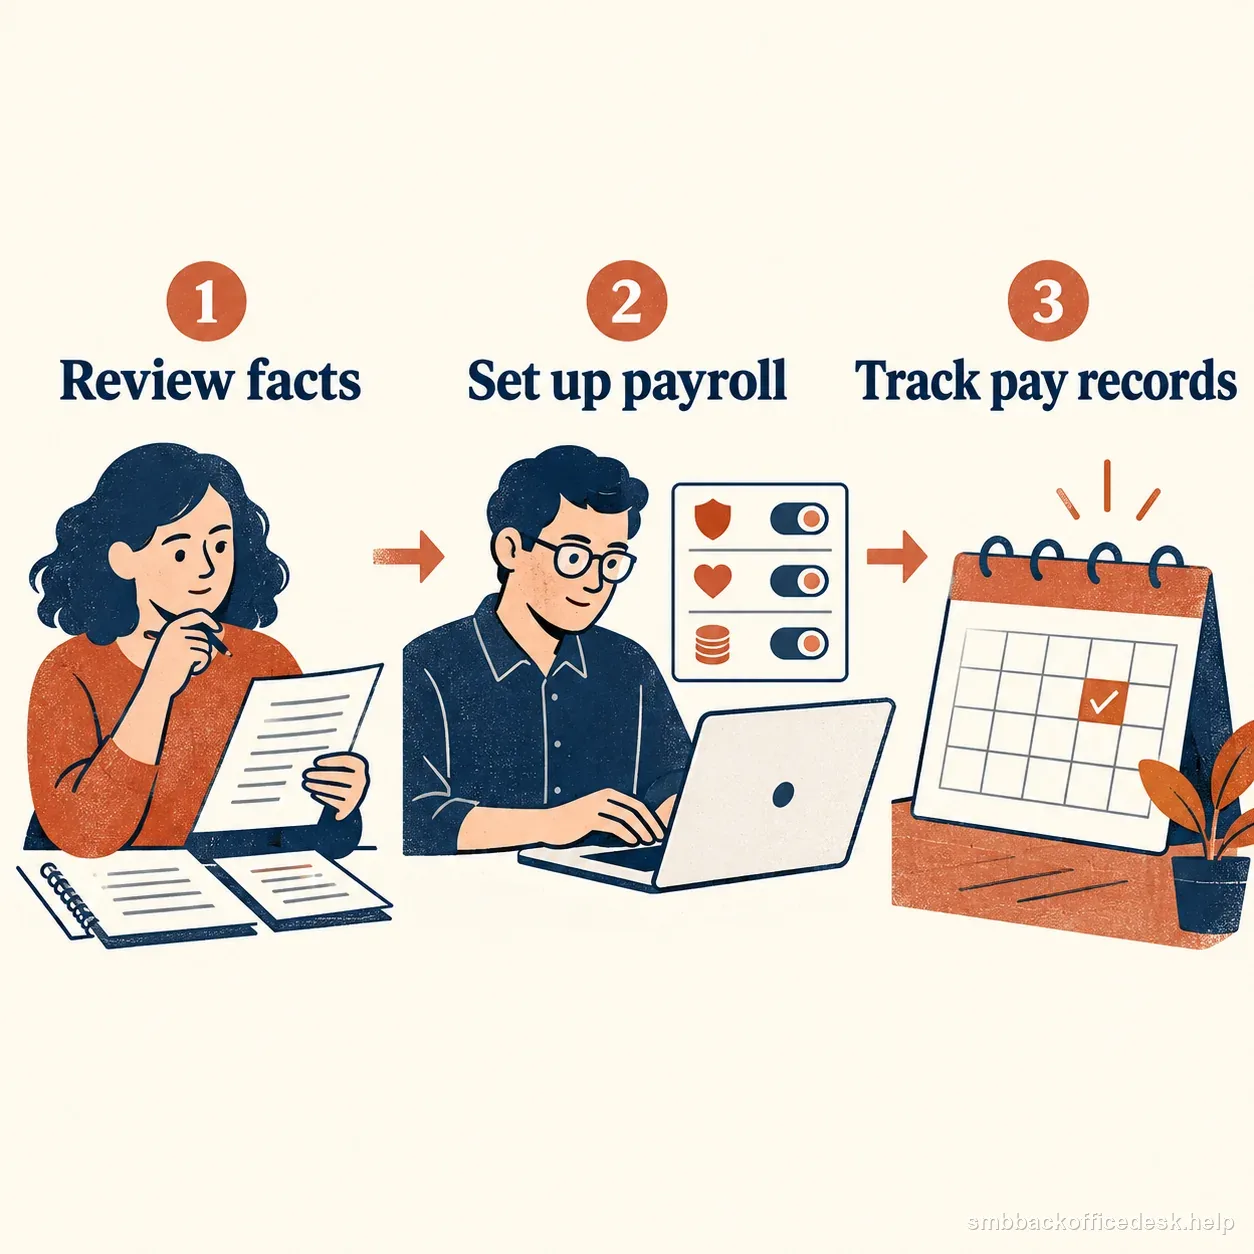
Use the effective date to coordinate onboarding and payroll records.
Move the operating relationship into the employee system
Assign the manager, job description, schedule, expense policy, security access, and performance process used for comparable employees. Review eligibility for benefit plans instead of assuming a former contractor is excluded.
Check workers’ compensation coverage and state unemployment accounts. A company hiring its first employee in a state may need registrations that were unnecessary when it only purchased services from a vendor.
Also revisit equipment and reimbursements. If the business now requires the employee to use certain tools or incur work expenses, federal and state reimbursement rules may apply differently.
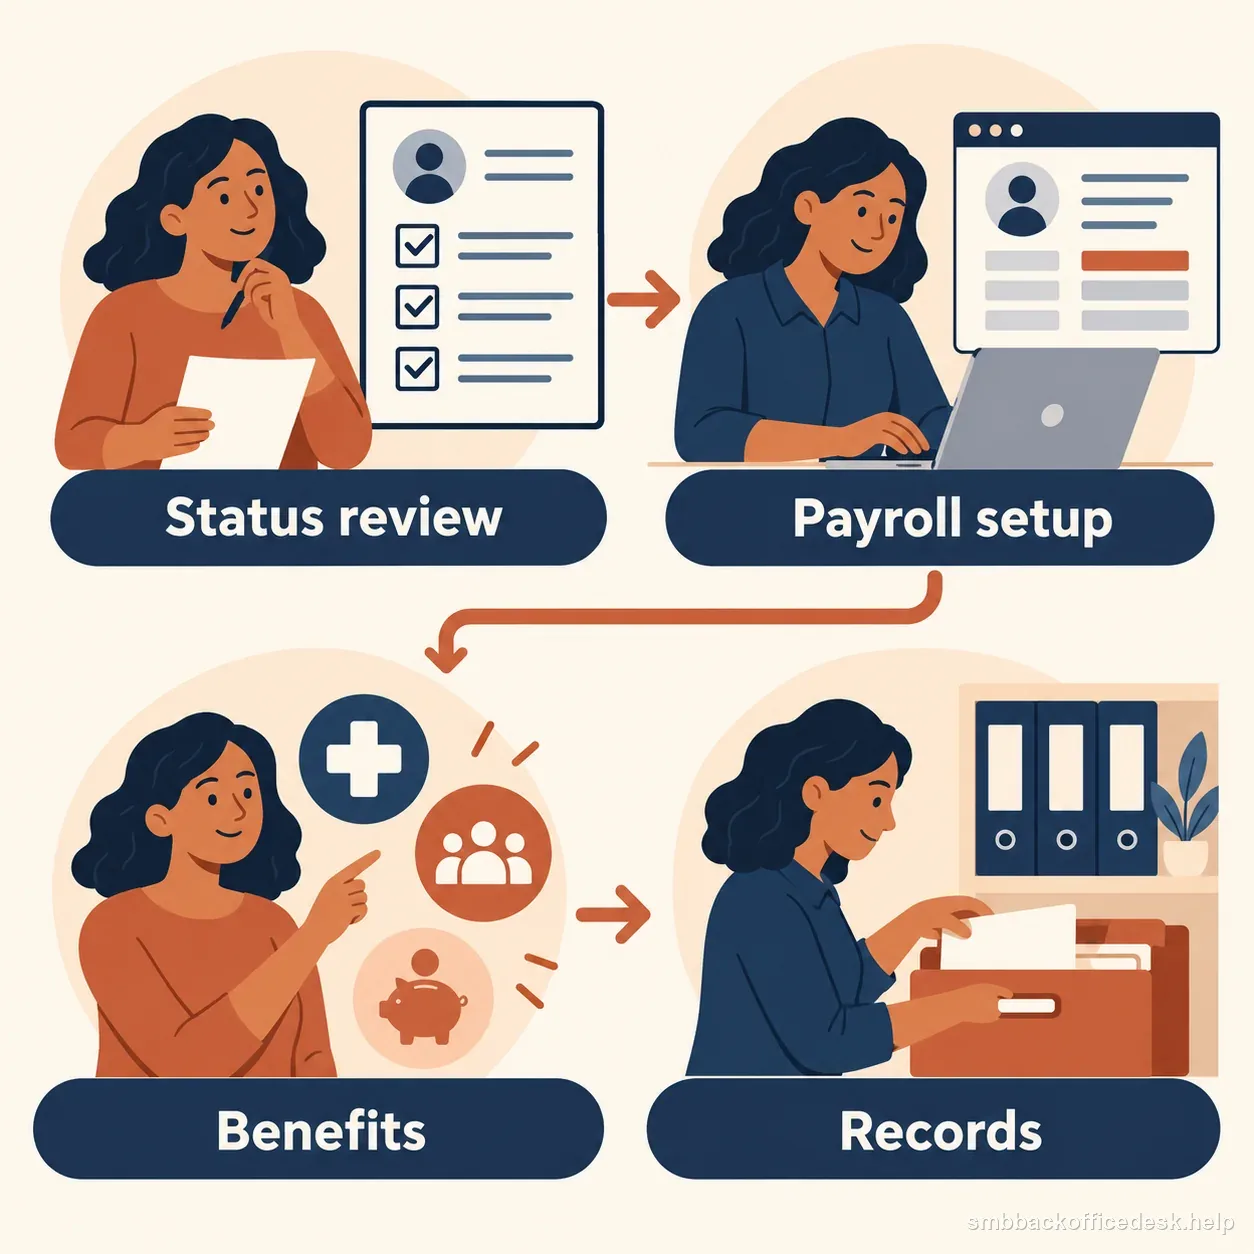
Review access, benefits, coverage, expenses, and the manager process as part of the transition.
Handle the split year correctly
A person can legitimately receive both Form 1099-NEC and Form W-2 for the same calendar year when the facts support distinct contractor services and employee work. In a conversion, this often means genuine contractor services before the effective date and employee services afterward; the date on a form alone does not establish that the periods were properly classified.
Do not allocate payments between the forms merely to reach a preferred tax outcome. Keep service date, invoice date, approval date, and payment date in separate fields, then apply the instructions for the reporting year. The IRS describes Form 1099-NEC as reporting qualifying payments made during the year for services by people not treated as employees; employee wages generally belong on Form W-2. Reporting thresholds and due dates depend on the tax year, so check the current IRS instructions before filing. A late invoice or payment crossing the effective date does not, by itself, settle the reporting treatment. Reconcile the underlying facts with the payroll or tax adviser before issuing either form.
For the employee period, withhold and deposit payroll taxes through the company’s normal payroll process and include wages on Form W-2. For the genuine contractor period, apply the information-reporting rules that govern nonemployee compensation. Keep the conversion memo with the payment ledger so year-end reporting can be reconciled.
| Contractor period | Employee period | |
|---|---|---|
| Work basis | Services actually performed before conversion | Employee work after effective date |
| Payment path | Valid contractor invoice/reporting | Payroll withholding and wages |
| Control | Do not backdate or force preferred tax result | Do not route employee services through vendor pay |
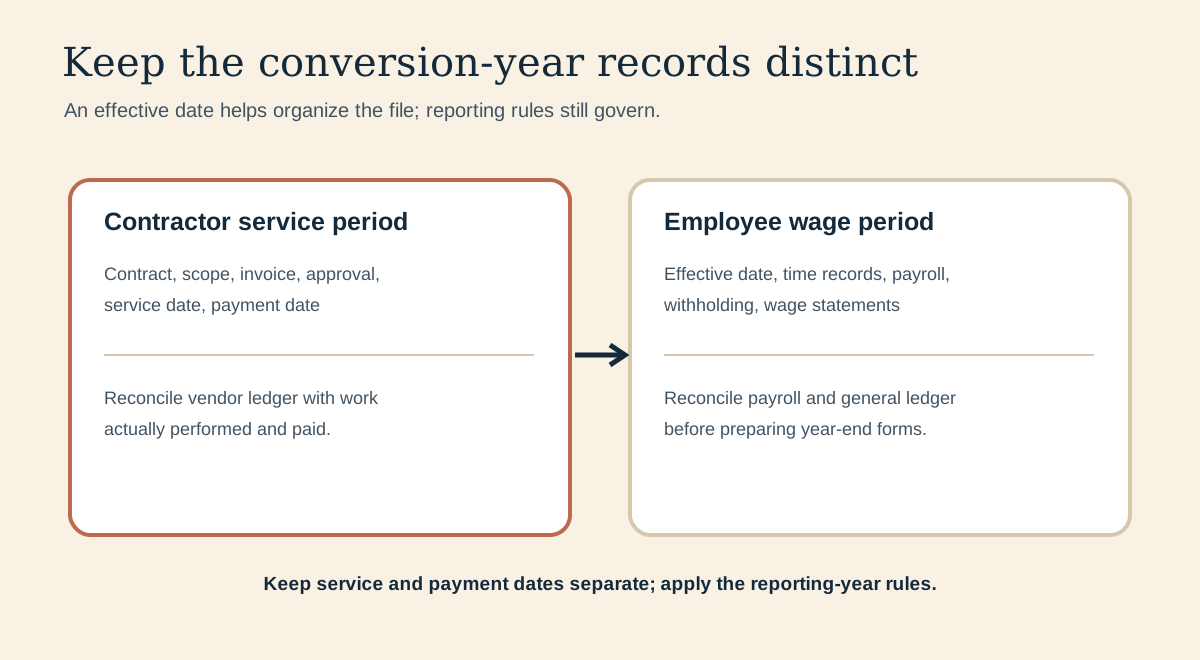
Separate vendor and payroll records while preserving service and payment dates for year-end reporting.
Review the past without assuming the conversion cures it
Moving someone to payroll today does not automatically resolve whether they should have been an employee last year. Record whether the work facts changed or only the company’s paperwork changed. If the earlier duties, instructions, schedule, and business arrangement were substantially the same, consider a historical classification review. Do not backdate the conversion or use today’s decision as a conclusion about an earlier tax year.
For federal tax exposure, questions may include amended employment-tax returns, Section 3509 calculations, Section 530 relief, or eligibility for the IRS Voluntary Classification Settlement Program. The VCSP is an optional, prospective federal employment-tax program with eligibility requirements and a closing agreement; Form 8952 is the application. Current IRS instructions call for filing at least 120 days before the requested start date. That lead time and eligibility review matter, so do not assume a routine payroll conversion qualifies or resolves earlier periods.
State withholding, unemployment, workers’ compensation, wage-and-hour, or benefit obligations may need separate analysis. A federal tax solution is not a universal settlement.
| Step | What to do | Notes from the guide |
|---|---|---|
| Effective date | Write down the date, role, manager, compensation, work location, and reason for the change | Do not backdate the start date to make records look cleaner |
| Form W-4 | Collect it before the employee starts under the new status | Follow current IRS instructions |
| Form I-9 | The employee completes Section 1 by the first day of employment and not before accepting the offer; the employer completes Section 2 within three business days after the first day of work for pay | If the job lasts fewer than three business days, Section 2 is due by the first day; follow current USCIS instructions |
| Payroll and state setup | Legal name, Social Security number, work location, pay frequency, compensation, and withholding elections; state and local withholding and new-hire reporting | Use the employee's actual work state |
| Nonexempt roles | Timekeeping, overtime, meal and rest rules, paid leave, and wage statements | Governed by the applicable jurisdiction |
| Coverage accounts | Workers' compensation and state unemployment accounts | A first employee in a state may need registrations that were not needed for a vendor |
| Year of conversion | Track service periods, invoices, and payment dates separately; apply the reporting rules for that year | Do not decide from the effective date or invoice date alone |
| Prior periods | Consider a historical classification review, which may involve amended returns, Section 3509, Section 530, or the IRS Voluntary Classification Settlement Program (Form 8952) | VCSP has specific eligibility rules, so do not assume every conversion qualifies |
Communicate the change clearly
Give the worker a written notice explaining the effective date, pay basis, payroll schedule, withholding, benefits information, timekeeping requirements, expense process, and who to contact with questions. Avoid telling the worker that W-2 treatment automatically means they will take home less or more; withholding and individual tax circumstances vary.
If compensation is being renegotiated because the company will now bear employer payroll taxes or offer benefits, document the new wage independently from the classification conclusion. An employee must still receive all wages required by applicable law.
Close the contractor setup
Stop future contractor invoices for employee work after the effective date. Disable duplicate vendor-payment routes that could accidentally send off-payroll compensation. Reconcile outstanding contractor invoices for services completed before conversion.
Update vendor-management records so the worker is not simultaneously treated as a supplier and an employee for the same services. Preserve prior contracts and invoices; do not delete them simply because the relationship changed.
Schedule a post-conversion check
After the first payroll and again before year-end, verify withholding, tax deposits, work-state setup, time records, benefits, expense reimbursements, and the split between pre-conversion contractor payments and employee wages.
A clean conversion has three distinct records: why the status changed, exactly when payroll treatment began, and how prior periods were evaluated. That record is far more defensible than quietly replacing a 1099 with a W-2 and hoping nobody asks when the relationship actually changed. For an IRS tax-status review, see the three-category worker-classification guide; the Form SS-8 overview explains the determination route.
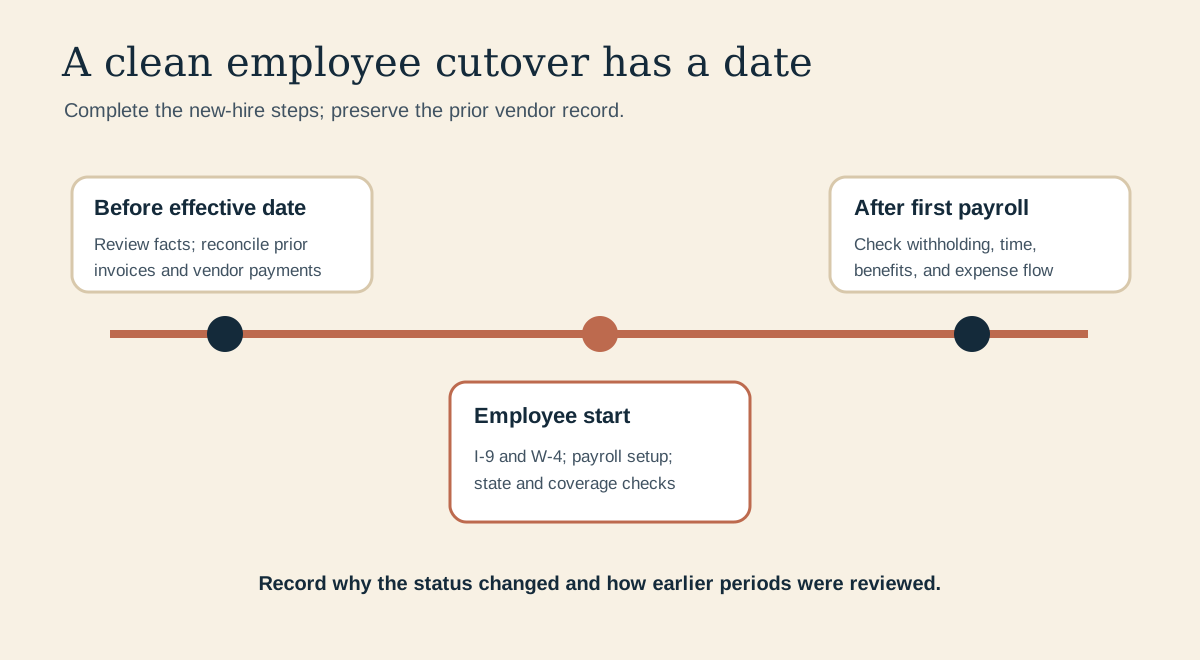
A dated sequence links the pre-conversion vendor file, employee start documents and a first-payroll review.