Winning a small-claims case creates a judgment, not an automatic bank transfer. The court generally does not collect the money for you. The next steps depend on the jurisdiction’s waiting periods, appeal or set-aside rights, and enforcement procedures.
Read the judgment notice before contacting anyone
Confirm: - judgment amount; - judgment debtor’s exact name; - date entered; - costs or interest included; - deadline for appeal or motion, if any; - date enforcement may begin; - whether the court requires any immediate post-judgment form.
Do not start garnishment merely because the judge announced a decision in court. California, for example, tells creditors to wait until the 30-day period to appeal or vacate has passed before beginning collection. Other states have different timing. Compare the written judgment with what the judge awarded; if the debtor name or amount is wrong or incomplete, ask the clerk about the local correction process before you give the judgment to an enforcement officer.
- Judgment enteredCheck amount, debtor, challenge, enforcement dates.
- Eligible to collectRequest payment or use lawful process.
- Payment receivedReconcile direct, court, or officer record.
- Paid in fullFile satisfaction and release liens if required.
Send a clean payment request
Once appropriate, send the debtor a copy of the judgment or identify the case, amount due, and payment method. Provide a short deadline to propose payment.
If installments make business sense, document the schedule and how payments will be applied. Understand whether the agreement changes your enforcement rights before accepting a new settlement contract.
Do not add collection fees simply because collection is inconvenient. Recoverable post-judgment interest and enforcement costs are governed by state law.
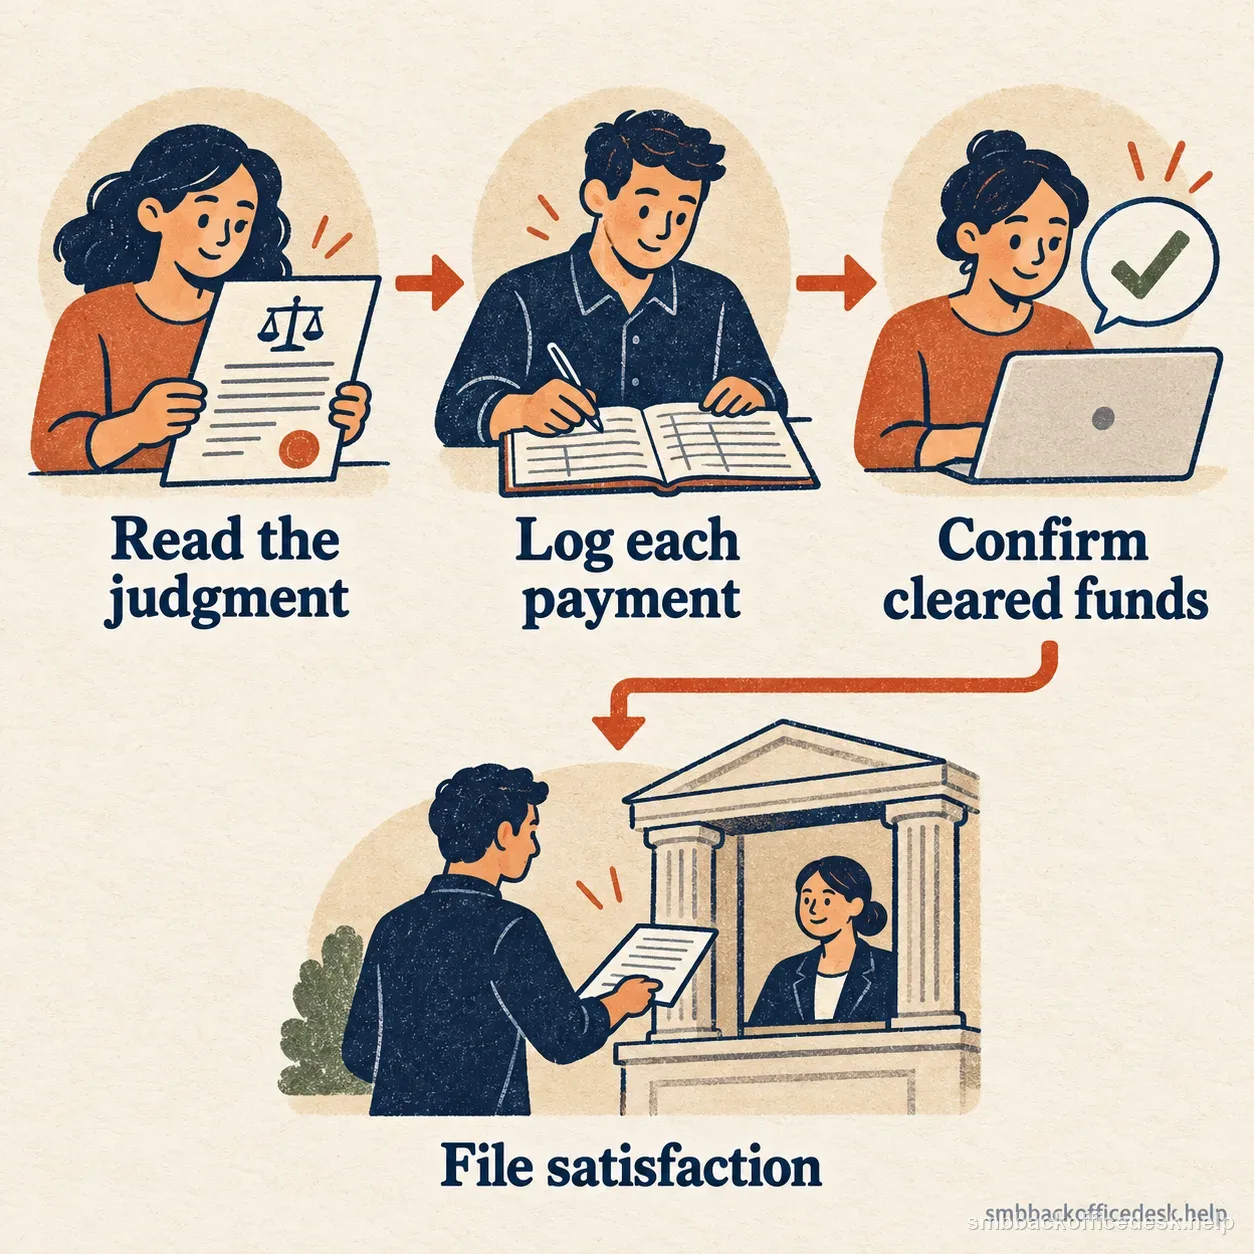
Track each allowed step in order; record satisfaction only after the full judgment amount is paid.
Track every post-judgment payment
Create a judgment ledger separate from the original invoice: - judgment principal; - awarded costs; - post-judgment interest if applicable; - enforcement costs the law allows; - payments; - balance.
Keep the supporting bank or court records. Record each credit against the judgment and recalculate the unpaid balance before requesting further collection.
Illustrative partial-payment ledger
Suppose the signed judgment states a total of $1,840, including $1,750 awarded principal and $90 in costs the court expressly awarded. The debtor later makes two cleared payments: $500 and $300. The ledger calculation is $1,840 − $500 − $300 = $1,040 still unpaid. This hypothetical excludes post-judgment interest and any later enforcement costs; add them only when the judgment and local law authorize them and the amount can be documented. Keep the judgment, each payment confirmation, the running balance, and any payment agreement together. Do not mark the case paid in full while the ledger still shows a balance.
The amount is only a bookkeeping illustration. It does not tell you which costs or interest a court will award, whether a payment plan changes enforcement rights, or whether property is exempt. If a court or marshal holds funds, reconcile the remittance statement and authorized fees before demanding a remaining amount.
Choose the next step from the status you can prove
- If the judgment notice shows a waiting, appeal, or stay period, calendar the date and ask the clerk what collection step is permitted after it ends. A hearing result alone is not a green light to seize or garnish property.
- If the debtor proposes installments, put the dates, amounts, missed-payment handling, and any effect on enforcement in a signed agreement reviewed under local rules. Post each cleared payment separately.
- If no payment arrives, use lawful court procedures to learn what assets may be reached, then compare the likely net recovery with filing, service, officer, and time costs. Exempt property and bankruptcy protections still apply.
- When the full amount required by the judgment is received, submit the local satisfaction form and keep proof it was filed. A partial payment does not close the judgment.
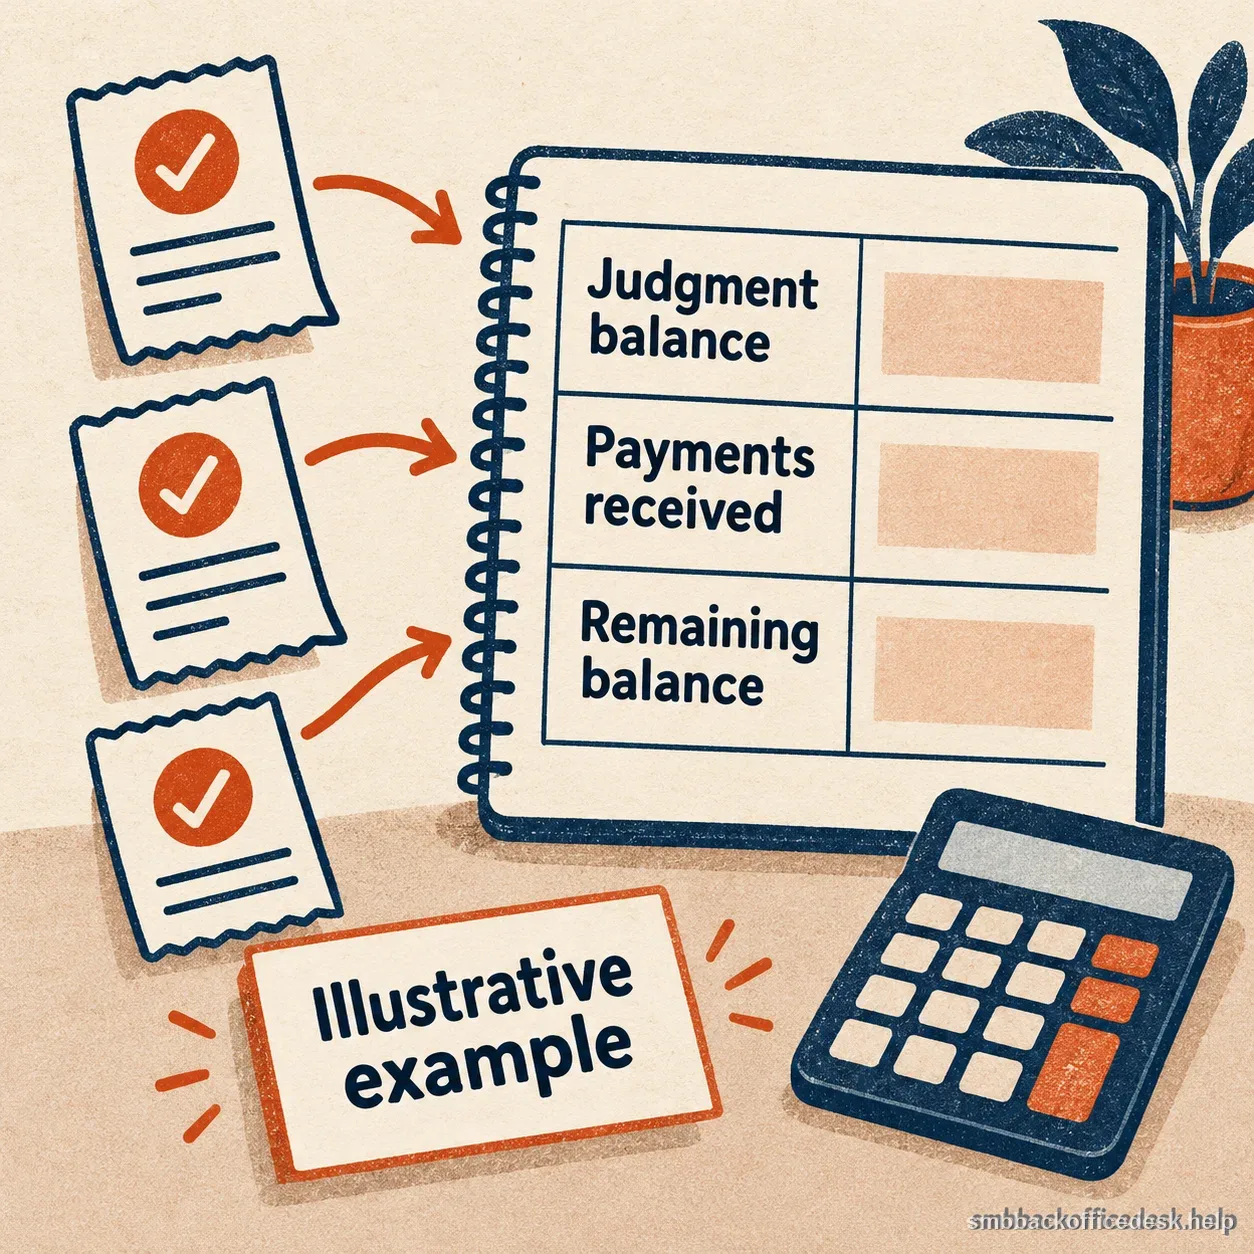
A dated ledger helps reconcile the judgment balance, cleared payments, and remaining amount.
File satisfaction when the judgment is paid
Courts require creditors to acknowledge payment. California uses Acknowledgment of Satisfaction of Judgment (SC-290) in small claims. Failure to file required satisfaction paperwork can create problems for the debtor and potential consequences for the creditor.
Do not wait months because the relationship was unpleasant. Once paid, close the judgment correctly.
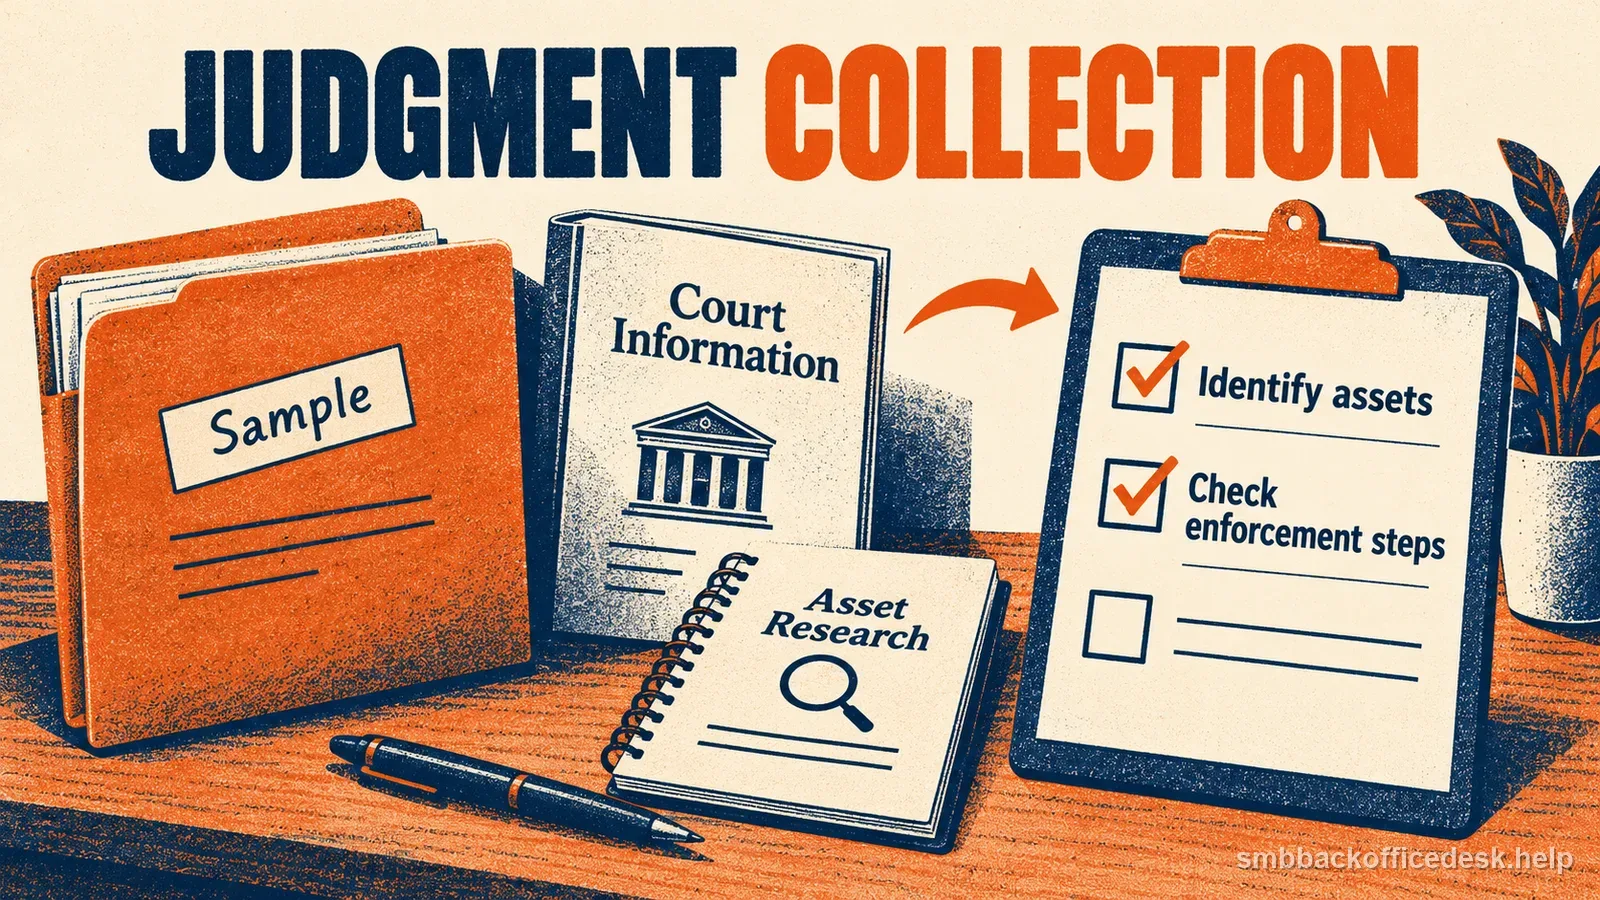
If the debtor does not pay, investigate assets lawfully
You need to know where the debtor has reachable assets. Depending on state law, tools can include judgment-debtor disclosures, debtor examinations, subpoenas for financial information, bank levies, wage garnishment, or liens.
California small-claims procedures can require a judgment debtor to provide a Statement of Assets (SC-133) after the relevant period, and the creditor can use court procedures to obtain more information when the debtor does not cooperate.
New York City’s court guidance describes sheriffs and city marshals as enforcement officers and lists methods including wage or bank garnishment and liens or seizure under applicable rules.
Those are jurisdiction-specific examples. Use your state’s enforcement forms.
Decide whether collection economics make sense
Before paying for an enforcement officer, transcript, lien, or asset search, estimate the likely return. A business with no assets, no bank account you can identify, and no continuing operations may be difficult to collect from.
Check whether the judgment can be renewed and how long it remains enforceable in your jurisdiction. Calendar deadlines so a collectible judgment does not expire through inattention.
Settlement can remain rational after judgment. A debtor may pay a discounted lump sum faster than a full balance collected over months. Document any compromise and file satisfaction only when the agreed condition is met.
Avoid prohibited self-help
A judgment does not give you permission to seize property yourself, access private bank data, harass the debtor, or contact unrelated people in a way the law prohibits. Use the court and authorized enforcement process.
If the debtor files bankruptcy, collection activity can be affected by the automatic stay and bankruptcy rules. Stop ordinary collection and obtain appropriate legal guidance.
The post-judgment file should contain the signed judgment, enforcement eligibility date, payment requests, ledger, asset information obtained lawfully, enforcement forms, receipts, and final satisfaction. Winning becomes valuable only when those steps convert the judgment into payment without creating a new legal problem.
Reconcile the payment route before closing the judgment
A debtor’s payment proposal, a court-held payment, and an enforcement officer’s remittance are different records. For a direct transfer, wait for cleared funds and retain the remittance details. If the debtor pays through the court, follow the clerk’s instructions to claim money already received; California’s SC-145 process is one example. Do not demand again an amount the court is holding.
If a sheriff or marshal collects, obtain the officer’s statement and reconcile the gross amount collected, authorized fees, net remittance, and any balance still due. Ask the issuing office about an unclear deduction before changing the account or sending another demand. When the full judgment is paid, follow the court’s satisfaction process; California uses SC-290. Keep the filed acknowledgment with the judgment and final payment record.
For a business creditor, assign one person to maintain the post-judgment file and record every contact attempt with its date, channel, and result. Keep original receipts and court notices in a read-only folder; work from copies when preparing an enforcement packet. If the debtor is a company, verify the legal entity named in the judgment against the filed business record before directing process to an address or related entity. A trade name, storefront sign, or parent company name may not be interchangeable with the party the court actually ordered to pay. Ask the clerk or a qualified local adviser about correcting a genuine mismatch instead of informally changing the debtor name.
Before paying an officer or filing another request, update the ledger and make a short decision note: amount still due, information supporting a reachable asset, expected fee, and the next deadline. If the likely recovery is small or asset information is stale, check whether a lower-cost court information step is available first. Revisit that decision when new facts arrive; a temporary inability to pay and a permanently uncollectible judgment are not the same finding. Keep the language in any payment demand factual and calm, and use only contact methods allowed by the judgment, court rules, and applicable law.
| Path | Reconcile | |
|---|---|---|
| Direct | Bank receipt | Debtor remittance |
| Court | Court receipt | Claim/payment process |
| Officer | Collection statement | Fees and remitted amount |